


Compliance
Why Europe holds the key to a fairer deal for HNW savers in 2014
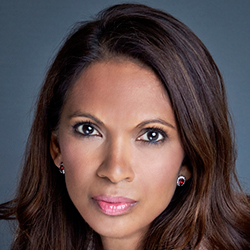
Gina Miller launched the True and Fair Campaign two years ago, calling for a fundamentally fairer deal for savers and investors. Her efforts have recently borne fruit.
In this article, Gina Miller describes the need for a fairer
deal for savers and high net worth investors, having launched the
True and Fair Campaign two years ago.
The call for an end to the rip-off of hidden costs and fees in
the UK fund management and pensions industry has gained
considerable support from politicians, users of the industry and
the media, with a noticeable change in the tone and language
emanating from the industry on the subject, but there is still
much to do to give these words substance.
When we launched the True and Fair Campaign two years ago, we
alone in calling for transparency and change and for a
fundamentally fairer deal for savers and investors. Our demands
for the fund management industry to reveal 100% of the costs and
fees they were levying for managing savers’ money, and also to
publish 100% of their holdings online, were met with ridicule.
The Investment Management Association (IMA) denied there was any
such thing as hidden costs and fees and accused us of
scaremongering.
They have since changed their tune and pledged to address this
issue, yet we are still waiting to see the details and hidden
costs and fees remain as much a feature of the fund management
industry today as they have ever been.
However, where the UK’s fund management industry has failed to
act, the European Union (EU) has stepped in to the breach. In
November, it delivered a very welcome early Christmas present for
hard-working savers when the European Commission voted for the
Packaged Retail Investment Products (PRIPS), to include an online
calculator that would show all costs, at all levels.
This seemingly simple act has major ramifications. Presenting
100% of all costs and fees, and allowing savers to compare these
outgoings against the real returns that flow from the products
before they part with their hard-earned money will be a major
step towards the empowerment of consumers.
Every other industry has already satisfied this basic right that
all consumers should have. Their inherent prerogative to know how
much something costs and what it will mean for them is hardly a
revolutionary one. Yet the amount of debate and angst that our
campaign for this basic right has generated would suggest that
the fund management industry begs to differ.
We believe strongly in the need for an online calculator that can
'reveal all' and enable consumers to calculate the costs of
investments and compare them with the returns they generate. We
think that prospective investors should find it easy to measure
risks and performance. In fact we think it is so vital that in
2013 we put our money where our mouth was and invested £250,000
of our own savings as well as our time and planning skills to
develop the algorithms and programming for a free, independent
online fund costs and fee comparison calculator, to be found at
www.trueandfaircalculator.com. This calculator lists more than
7,500 products, among them investment trusts, ETFs and unit
trusts, and allows users to enter their own portfolios when in
'advanced' mode.
Even though we do not have an advertising budget, this True and
Fair Calculator has had more than 50,000 page visits from users
all over Europe and indeed from places as far-flung as Canada,
Australia, India and America, all struggling to find out what
they pay and how different products or portfolios compare with
one another. It reveals very clearly what different fund managers
are charging and how these charges affect returns on savings and
investments.
Although this True and Fair Calculator has gained both political
and sector-wide support, it has also been a target for brickbats
in equal measure from those who would prefer that consumers only
had partial transparency on costs and fees.
Yet in all this one vital element seems to have been lost – the
views of the consumers themselves.
We commissioned research back in January 2012 among a
representative sample of more than 2,000 British adults and the
results were shocking. They revealed that just 19% of investors
(less than one-in-five) knew what they were paying in fund
management fees.
This does not paint the picture of an industry that has engaged
consumers and succeeding in putting transparency of costs and
fees at the heart of everything that it does. The research also
revealed that 89% of savers and investors liked the idea of fund
managers offering full breakdowns of fees, with 83% wantng to
know where their money was being invested.
These wishes are still not being fulfilled in the UK, or
elsewhere in Europe, which is why the European Parliament’s vote
to include an investment calculator within the PRIPs is so
important, and why we hope that the Council of Ministers (one of
the organs of the EU that rubber-stamps the decisions of other
organs) will support the legislation when it comes before it in
2014.
If it does so, this will be a significant victory for the
protection of consumers from sharp practice. It is not an
exaggeration to say that if the EU legislates to require the
total disclosure of each fund's costs and charges in a single
figure, and if it makes an online calculator compulsory, then we
could see a significant boost to both pension savings and wealth
in general.
A recent report by the RSA2 (Royal Society for the encouragement of Arts, Manufactures and Commerce) found that if a typical Dutchman and a typical Englishman were to save the same amount for their pensions, the Dutchman could expect 1½ times the Englishman's income in retirement.
Other commentators have suggested that up to half the value of a pension fund can go on costs and fees, yet most savers do not realise this and have little understanding of how much they pay, or what they get for their money.
Since 2008 few funds have generated stellar returns, yet many continue to take the same fees. It is more vital than ever to prove the link between cost and performance because the market is performing better and better and the stakes are therefore higher.
Despite this the IMA and the UK fund management industry has yet to make costs and fees totally 'transparent' or to even to discuss the merits or not of supporting a practical solution to the problem, such as www.trueandfaircalculator.com.
There has been a lot of talk yet the situation for savers today is no better than it was in 2008. There is simply no transparency.
When announcing its intention to look at introducing PRIPs, the European Commission (the nearest thing that the EU has to an executive) stated: "The financial crisis has become a crisis of consumer confidence. Lack of transparency, low awareness of risks, and poor handling of conflicts of interest have meant that consumers across the EU have been repeatedly sold investment and insurance products that were not right for them. Only by taking steps to tackle these shortcomings can low consumer confidence be tackled, laying strong foundations for growth in the EU."
The EU has taken significant steps to remedy these shortcomings. When one looks at PRIPS in conjunction with other text from MIFID II (the Markets in Financial Instruments Directive) that calls on firms to display costs and fees in one understandable number, we are very hopeful that 2014 will produce the final piece of the jigsaw and give savers across Europe 100% transparency on all costs and fees – something they have every right to demand and expect.
The irony is that this reform will strengthen the very fund management industry that is so reluctant to embrace it. It is time for it to stop arguing, back the EU’s initiative and grab the prize.
* Gina Miller is the founder of the True and Fair Campaign and SCM Private