


Real Estate
The Hotel Looks Like Real Estate – The Risk Lives In The Operation
For family offices considering direct hotel ownership, the decisive underwriting question is not only what the property is worth. It is whether the operating business can produce the return.
The following article comes from Marty McDaniel (pictured
below), who is chairman and CEO of The Northstar
Companies. The piece is written for family offices
evaluating direct hotel ownership and looks at the risk that can
get obscured when a hotel is underwritten primarily as real
estate. Management depth, labor, franchise obligations, revenue
execution and reinvestment can alter the return profile quickly,
even when the underlying property and market look sound. The
editors are happy to share these insights; the usual editorial
disclaimers apply. To comment, email tom.burroughes@wealthbriefing.com
and amanda.cheesley@clearviewpublishing.com
Marty McDaniel
A hotel can look reassuringly familiar to a family office. There
is land. There is a building. There is often a recognizable flag
on the sign. There are comparable sales, replacement costs and a
capital plan. On paper, it can read like real estate. In
practice, it behaves more like an operating company that happens
to own a very expensive piece of real estate.
That distinction matters because family offices are not strangers
to private assets. UBS reports that alternative assets account
for 42 per cent of family office allocations, including private
equity, real estate and private debt. It also reports that 77 per
cent of the families surveyed still have an active operating
business. (1)
Many of these investors therefore understand operating risk
intuitively. The mistake is assuming that a hotel can be managed
with the same degree of passivity as a leased building.
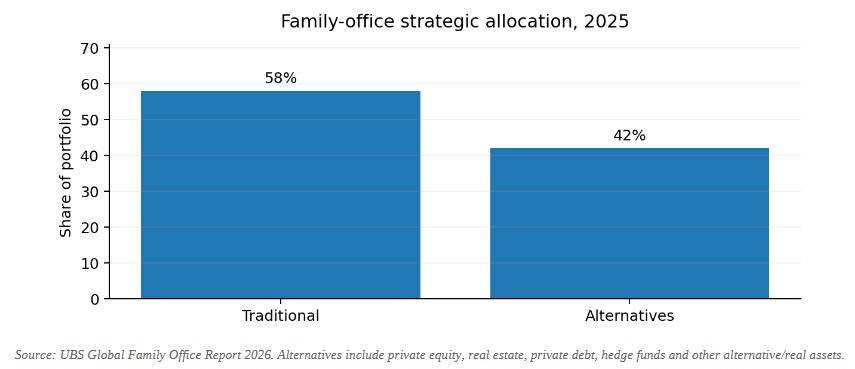
Source: UBS Global Family Office Report 2026. Alternatives
include private equity, real estate, private debt, hedge funds
and other alternative/real assets.
I have spent nearly four decades in hotels, and the easiest way I
know how to explain the risk is this: the building sets the
stage, but the operation writes the check. A great location can
survive mediocre execution for a while. A good brand can cover
mistakes for a while. Neither can permanently overcome weak
leadership, poor revenue strategy, labor inefficiency, deferred
maintenance or a capital plan that exists only in a
spreadsheet.
Underwrite the operator, not just the asset
Traditional real-estate diligence asks whether the market
supports the asset. Hotel diligence must go one step further and
ask whether the operating team can actually convert that market
into profitable demand. In Q2 2026, US hotel demand grew 1.7
per cent year-over-year while supply increased only 0.4 per cent;
ADR rose 4.4 per cent and RevPAR 5.7 per cent. (2)
Those are constructive market signals, but they do not mean that
every hotel participates equally. The gap between market growth
and asset-level performance is where operating quality shows
up.
Before a family office buys a hotel directly, I would want a
clear answer to five operating questions: Who is accountable for
revenue strategy? Is labor scheduled to demand or to habit? What
is the real condition of the building behind the engineering log?
What brand obligations or property-improvement requirements are
coming? And can the management team explain, in plain English,
how the property will produce the underwritten cash flow?
The answer should not be a 40-page budget. It should be an
operating thesis that connects rate, occupancy, channel mix,
labor, food and beverage, maintenance, capital and guest
experience. A hotel does not have independent departments. It has
one economic engine with a lot of moving parts.
The quiet risk is capital that arrives late
Hotels wear out in public. Guests see the tired corridor, the
slow elevator, the worn carpet and the room that should have been
out of order before they checked in. Deferred capital eventually
becomes a pricing problem, a guest-score problem, a labor problem
and, in branded hotels, potentially a franchise problem.
That is particularly important now because hotel transactions are
accelerating while a large amount of hotel debt approaches
maturity. JLL reports $24 billion of US hotel transaction volume
in 2025, up 17.5 per cent year-over-year, and about $88 billion
of hotel loans scheduled to mature through 2027. (3)
Buyers will see opportunities created by refinancing pressure,
capex needs and ownership transitions. Some will be genuine basis
opportunities. Others will simply be undercapitalized operating
businesses wearing attractive real estate.
A family office with patient capital can have an advantage here.
It does not have to force a three-year exit, and it can fund a
sensible renovation or repositioning without manufacturing
short-term performance. But patient capital still needs impatient
operating discipline. The longer the intended hold, the more
important it becomes to know whether management is protecting the
physical asset, the brand, the team and the cash flow at the same
time.
Direct ownership requires direct governance
The best hotel investments I have seen were not micromanaged by
ownership. They were governed well. Ownership knew which
decisions belonged to the operator, and which decisions could
change the investment thesis. They monitored a small set of
leading indicators, not just last month's P&L. They made
capital decisions before the building forced them to. And they
treated management depth as part of the asset, not an HR
issue.
That is the real opportunity for family offices considering
direct hotel investment. Hotels can offer scarcity, inflation
sensitivity, multiple demand segments, daily pricing and tangible
real estate. They can also provide something that many passive
assets cannot: operational upside. JLL expects constrained
supply, stronger debt-market liquidity and active private-equity
interest to support a new hotel investment cycle in 2026. (4)
Operational upside, however, is only
valuable
if the owner is prepared to govern an operating business.
The conclusion is not that family offices should avoid hotels. It
is almost the opposite. A hotel can be a compelling direct
investment when the investor underwrites the operation with the
same rigor as the real estate. The mistake is buying one and
pretending those are the same thing.
About the author
Marty McDaniel, CHA, is a second-generation hotelier with 38
years of senior hospitality leadership across hotel and resort
operations, multi-property leadership, development, renovations,
revenue strategy, turnarounds and ownership-side advisory. He is
chairman and CEO of The Northstar Companies, a Certified
Hotel Administrator and an eCornell Revenue Management Expert.
His hospitality commentary and industry work have appeared in
Hotel Business, Lodging, Hotel Management, Hotel Online and other
hospitality publications. More at MartyMcDaniel.com.
Footnotes
1. UBS, Global Family Office Report 2026, May 28, 2026. The
report surveyed 307 family offices in more than 30 markets; it
reports 42 per cent of allocations in alternatives and notes that
77 per cent of surveyed families had an active operating
business.
https://www.ubs.com/global/en/media/display-page-ndp/en-20260528-global-family-office-report-2026.html
2. CBRE, “Hotel ADR & RevPAR Continue to Rise – US Hotel Q2
2026,” July 29, 2026.
https://www.cbre.com/insights/figures/q2-2026-us-hotel-figures
3. JLL, “Hotel investment momentum builds as US market posts $24
billion in 2025 transaction volume,” January 30, 2026; and
JLL, 2026 Global Hotel Investment Outlook, which reports $88
billion in hotel loans scheduled to mature through 2027.
https://www.jll.com/en-us/newsroom/jllreleases-2025-us-hotel-investment-trends-report
4. JLL, 2026 Global Hotel Investment Outlook, February 2026.
https://www.jll.com/en-us/insights/market-outlook/global-hotel-investment