


Asset Management
For Quant Investors, AI Is A Major Advance, With Caveats – Lazard AM
We talk to one of the portfolio managers at New York-headquartered Lazard Asset Management about the ways that AI affects the quantitative investment approach, pointing to the risks and opportunities.
AI has cut barriers to entry for the wealth sector's number
crunchers trying to spot lucrative investment opportunities amid
the data "fog."
This technology appears at first glance to be a harmonious match
for the quantitative approach to investing, a style that draws on
vast troves of data. "Quants" use mathematical models,
statistical analysis, and computer algorithms to select
securities and build portfolios.
Artificial intelligence enables quant strategists to test
hypotheses faster, which is important in rapidly shifting
markets, and it can extract information from previously
hard-to-reach areas. On the downside, users must distinguish what
large language models (LLMs) have uncovered from what they have
memorised; they must also watch for AI's tendency to identify
patterns that don't exist.
These are some of the observations from Boston-based Kurt
Livermore (pictured below), portfolio manager at Lazard Asset
Management, part of Lazard. He spoke recently to this news
service.
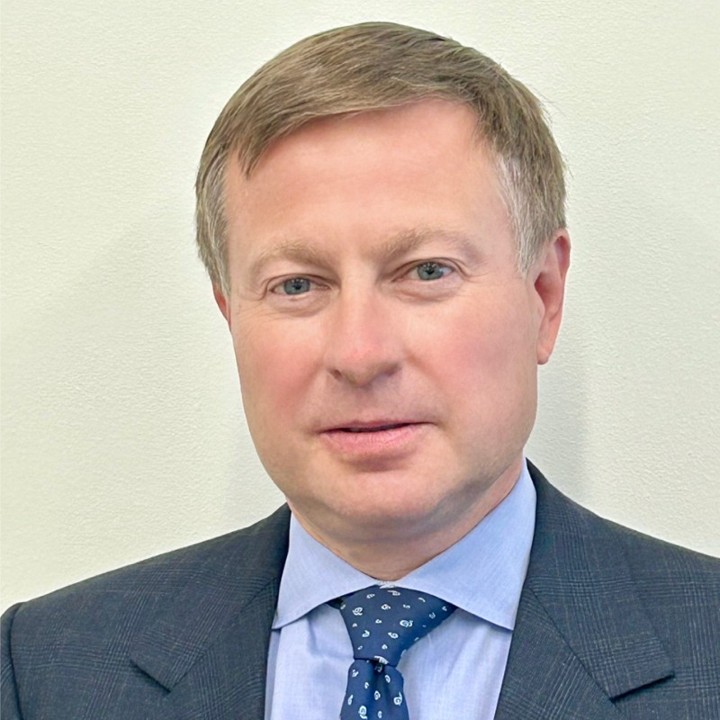
Kurt Livermore
We asked asked Livermore what wealth managers make of how
asset managers use AI.
"In the wealth channel, the conversation is robust. There is a
great deal of interest, but 'AI' is often used as a single
undifferentiated label covering everything from a chatbot to a
fully autonomous stock-picker. Much of our effort with private
banks, family offices and RIAs is therefore definitional:
distinguishing AI as a research tool within a disciplined process
from AI as a black box, explaining why we insist on an economic
rationale for every signal, and giving them the questions to ask
any manager, including us," he said. "Transparency about what the
tools do and do not do has generated the most interesting
conversations."
His views carry the weight of a business that, as of 31
March this year, had total AuM of $259 billion across
the Lazard group, according to results issued on 1
May.
Where has AI proven to be particularly
useful?
"Our starting premise is that markets are very good at pricing
information that is simple and widely observed, and much less
good at pricing phenomena that are complex, embedded in networks,
or absent from standard financial datasets," Livermore said. "The
data is rarely hidden; most of it is public. The difficulty is
that making sense of it requires connecting many weak, dispersed
pieces of evidence across companies, sources, and time. That is
precisely the kind of information markets absorb slowly.
"Every piece of research begins with a question about why a
particular kind of structural information might be mispriced.
Someone on the team articulates the mechanism: a company's
position in a patent-citation network, intangible investment that
accounting rules force firms to expense, the heterogeneous way a
macro shock transmits through supply chains.
"We write down what we expect to see and what would falsify it
before touching the data. Then the hypothesis is tested,
including on how slowly its edge fades after a portfolio is
formed. That decay profile is diagnostic: a signal capturing
genuine structural information should lose strength slowly; a
signal capturing something transient fades quickly. If the result
doesn't behave the way the hypothesis predicts, it doesn't enter
the model. The reason we insist on the hypothesis first is
that the alternative, letting the data generate the idea, is
where most spurious results come from. With enough variables you
will always find something that 'worked.' Requiring an economic
rationale is our main defence against that."
Livermore has worked as a quant portfolio manager for almost 30
years. He began his career in San Francisco, working at various
firms, and joined Lazard Asset Management three years ago.
The large toolkit
Quants use AI in various ways. This news service, appropriately
enough, used an AI search to bring up examples. These include
machine-learning return prediction, used at firms such as
Renaissance Technologies, D E Shaw and Two Sigma; natural
language processing, in which earnings call transcripts,
regulatory filings, news and other communications are scored for
sentiment, tone and changes in vocabulary to feed trading
signals; alternative data processing, such as using satellite
imagery, web traffic and shipping data to gain insights into
financial behaviour; and analysing portfolio risks and
correlations, among others.
Livermore said productivity is a big plus from AI.
"These tools write usable, robust code quickly, and that has
changed the economics of research. The constraint has moved more
in the direction of good ideas; the time it took to turn an idea
into a clean, tested implementation is much shorter. When that
cycle shortens from weeks to days, we can test more hypotheses,
kill the weak ones sooner, and spend more of the team's time on
the question of why something should work rather than on the
plumbing," he said.
The "reach" of AI is another advantage.
"The tools extract usable information from text we previously
treated as too noisy to use systematically. Something a human
could do for one company in an afternoon can be done for an
entire universe overnight, and done consistently," he said.
And the negatives?
"The first [negative] is how easily the tools will give you a
confident, well-fitted answer to the wrong question. The capacity
to find patterns is also a capacity to find patterns that aren't
there, and we have had results that looked compelling in-sample
and dissolved on contact with new data," Livermore said. "The
second is subtler and more dangerous for a backtest-driven
discipline: it is hard to separate what an LLM has uncovered from
what it has memorised. A language model trained on text up to a
given date has, in effect, read the newspaper for every year in
your backtest."
Today's market volatility can be overstated when set against
previous episodes, but the drama of daily headlines can still be
unsettling. This news service asked Livermore how
AI helps quants navigate such conditions.
"In volatile periods the information flow accelerates and the
value of being able to process it quickly and dispassionately
rises. Systematic processes do not panic, and that is an
advantage," he said. "The caveat is that models trained
predominantly on calmer regimes can be at their least reliable
precisely when conditions change. So, our approach is not to let
the tools run harder in a crisis but to lean more heavily on the
risk framework and on human oversight of what the signals are
telling us and why."
What happens to returns?
"Judging the difference AI tools make to returns in any specific
environment is difficult, and I would be cautious about any claim
that puts a number on it. A tool's contribution cannot be
separated cleanly from the signals it helped build, the risk
framework around them, and market conditions themselves, and the
period over which these tools have been in use is too short to
draw conclusions," Livermore said.
There are various claims made about how well AI-powered
investments fare. For example, in 2025, a report
(aistreet.beehiiv.com, March 2025, Bloomberg)
said Bridgewater Associates' $2 billion AI fund is, in the words
of its CEO Nir Bar Dea, generating "unique alpha that is
uncorrelated to what our humans do.” The article did not
disclose specific figures. Run by co-CIO Greg Jensen, the fund
combines Bridgewater's proprietary technology with plans to
include models from OpenAI, Anthropic, and Perplexity.
Bridgewater formed its Artificial Investment Associate (AIA) Labs
division in 2023.
In another case, that of M&G (Lux) Global Maxima Fund,
M&G was quoted saying in February 2025 that this portfolio,
which blends AI stock-picking recommendations with human
oversight, beat its benchmark, the MSCI ACWI Net Return Index,
over the five years from inception.
In general, however, it appears that while results from some
cases appear promising, it may be premature to uncork the
champagne just yet.
Kill or cure?
There is also the open question of whether AI is part of the
volatility story as well as a way of handling it.
"I'd stress this is a hypothesis rather than something we can
demonstrate. If many investors interpret the same event through
similar tools, they may reach similar conclusions at similar
times, which could in principle amplify market moves rather than
dampen them. That concern would be greatest where users lack the
expertise to evaluate the output and defer to it rather than to
their own judgment. Whether any of today's volatility reflects
this, we can't say. It is one more reason [why] we view AI as a
tool for testing hypotheses that can be defended on their own
terms, rather than as a source of market views,"
Livermore said.
Looking ahead, Livermore predicted that "nearly every manager
will describe itself as using AI, so the label will stop
differentiating and process discipline will matter more."
He argued that easily replicated applications, such as asking an
AI tool which stocks to buy, will see whatever edge they have
decay quickly as they become commoditised; the durable advantages
will sit in proprietary ideas, in how signals are combined, and
in how the research function is organised.
"The research cycle continues to compress. That is a productivity
gain, but it also raises the risk of explaining the past
perfectly and predicting nothing, so the firms that benefit will
be those that tighten their testing standards as throughput rises
rather than relaxing them," he said. "I expect the winning model
to be collaboration: humans generating and judging hypotheses,
machines testing them at a scale that was not previously
possible."