


ESG
Capitalising On Urgent Race To Cut Energy Consumption

The author of the article, who is based at Nordea in Denmark, argues that the electricity grid is where the AI boom, the energy transition, and the reshoring of industry physically collide. Addressing that bottleneck is likely to be an enabler of growth. Recent geopolitical turmoil adds to the calculation.
The following article is from Henning Padberg (pictured below), co-portfolio manager of Nordea’s Global Climate and Environment strategy. He addresses what he sees as the urgent need for countries to cut their reliance on fossil fuels, citing the interruptions to supply caused by the Gulf conflict, among other factors, as a major reason for countries to act.
The editors are pleased to share these views with readers. The standard editorial disclaimers apply to views of guest writers. To comment, email tom.burroughes@wealthbriefing.com and amanda.cheesley@clearviewpublishing.com
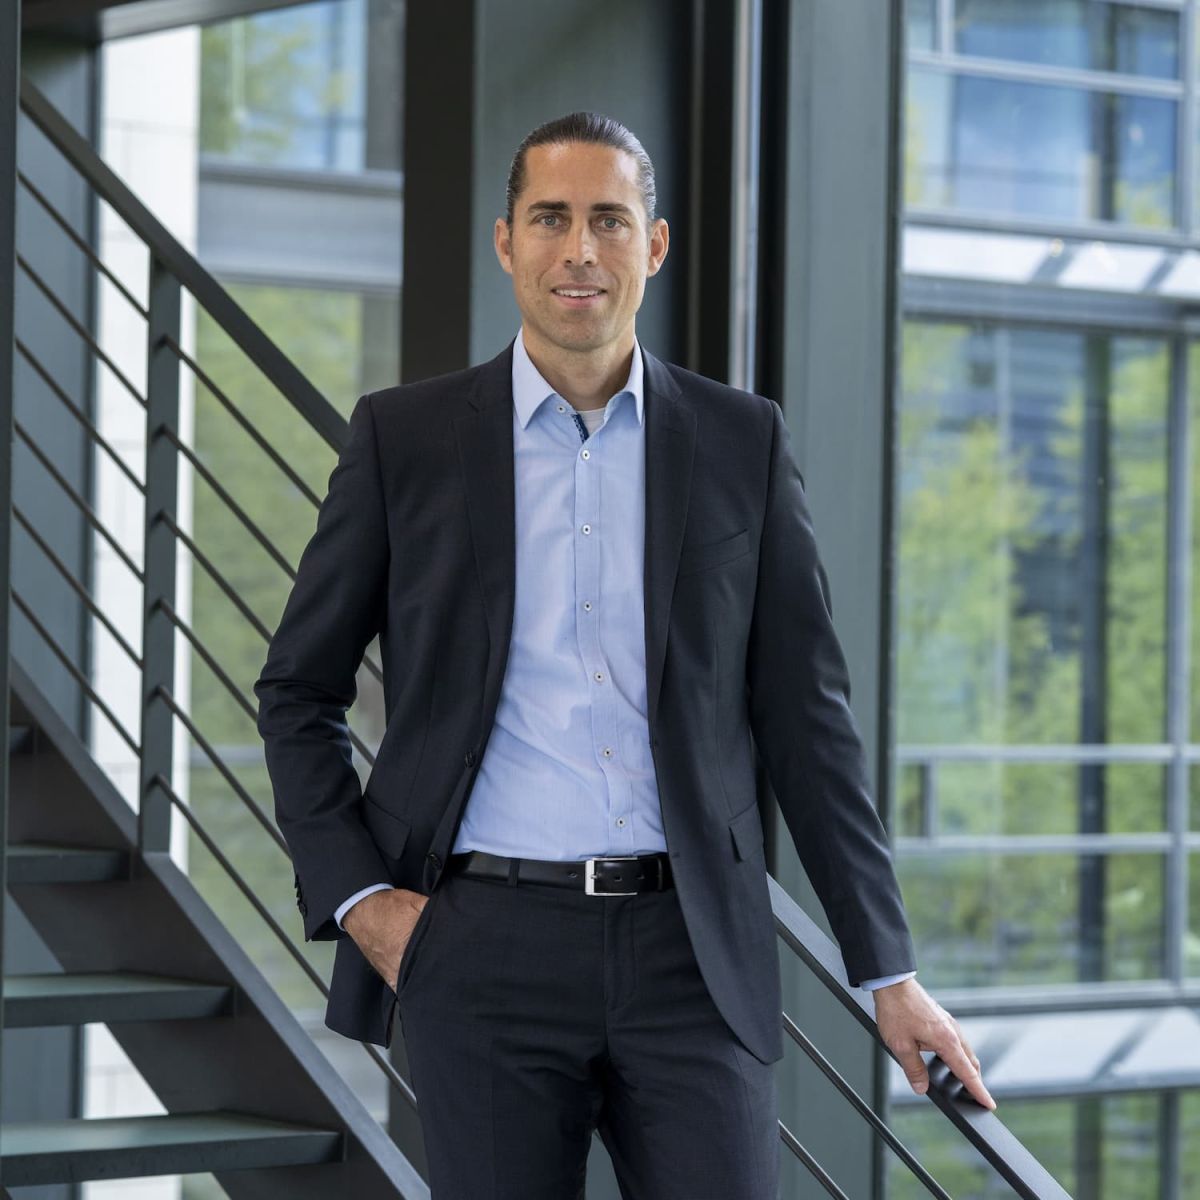
Henning Padberg
Recent events have once again highlighted a structural vulnerability the global economy has yet to fully resolve. When the Strait of Hormuz closed and the price of crude surged, governments reached for the usual responses: strategic reserve releases, rerouted pipelines, and emergency diplomacy.
The uncomfortable truth is that no reliable hedge exists against
fossil fuel dependence concentrated in politically volatile
regions. Supply can be diversified, but logistics or diplomacy
alone cannot fully manage the underlying exposure.
The only answer, which has rarely felt more relevant, is to use
less energy in the first place. For investors, this is one of the
most structurally compelling opportunities available today.
The energy race as AI accelerates
Resource efficiency is not simply a theme within our Global
Climate and Environment strategy, it is the dominant conviction,
accounting for approximately 70 per cent of the total allocation.
That reflects a long-held belief that the most economically and
environmentally compelling opportunities in the green transition
are not confined to generating new clean energy, important
as that is, but lie in dramatically improving the efficiency
of the energy systems, buildings, industrial processes, and
digital infrastructure we already have.
Within resource efficiency, two structural themes have emerged
with particular force this year. The first is the energy
efficiency imperative at the heart of AI. The AI race, which
began as a competition for raw computing power, has become an
energy race. For the world’s largest technology companies, energy
efficiency has moved from an environmental aspiration to a
board-level operational priority.
Data centre electricity demand is projected to roughly double
from approximately 485 TWh in 2025 to nearly 950 TWh by 2030, a
scale of consumption that already rivals Germany’s annual
electricity use. This demonstrates the importance of efficiency
solutions for cooling, which alone accounts for between 30 and 40
per cent of a data centre’s energy consumption. A leading
North American and European provider of climate control
solutions, Trane’s advanced HVAC systems reduce energy
consumption and are already deployed by major tech clients. The
company has also committed to reducing its customers’ carbon
footprint by 1 Gt of CO? by 2030.
Elsewhere, application-specific chip architectures, advanced
networking infrastructure, semiconductor manufacturing equipment,
and energy management platforms are all part of this story.
Need to modernise the strained grid
The second engine is the modernisation and expansion of the
electricity grid itself. AI-driven data centre growth,
electrification of transport and heating, and reshoring of
industrial capacity are placing enormous strain on ageing grid
infrastructure.
Global grid investment, which stood at around $300 billion
annually in 2020, has already risen sharply and is forecast to
total nearly $6 trillion globally between 2026 and 2035, with the
US alone absorbing roughly $1 trillion of that capital. Capacity
auction clearing prices in the largest US grid have surged to
record highs, jumping nearly tenfold in two years.
The companies enabling this physical buildout and modernisation
sit at the intersection of several major structural growth
themes. For example, these are engineering contractors laying
transmission lines and integrating renewable connections, cable
and equipment manufacturers supplying high-voltage systems in
acute global short supply, and regulated utilities deploying
capital on both sides of the Atlantic.
The grid is where the AI boom, the energy transition, and the
reshoring of industry physically collide. Addressing that
bottleneck is likely to be an enabler of growth. For example,
French energy management and industrial automation leader
Schneider Electric has enabled the avoidance of over 860 million
tonnes of CO2 [emission] cumulatively since 2018 through its
EcoStruxure platform. This open IoT (Internet if
Things) architecture delivers 10-30 per cent energy savings
in buildings and up to 25 per cent in industrial operations. It
is a compelling example of what it looks like to build an entire
business model around helping the world use energy more
intelligently.
About the author
Henning Padberg, who is based in Copenhagen, is a portfolio manager at Nordea. He is co-portfolio manager of Nordea’s Global Climate and Environment strategy. He has worked at the firm since 2008. Earlier, Padberg interned at the asset management and institutional clients’ businesses of JP Morgan. He was educated at the University of Münster, attaining a Master of Business degree.