


Alt Investments
Borrowing Vs Private Fund Portfolios: An Option Worth Understanding Before It's Needed
This article covers the intersection of fund finance and family office liquidity.
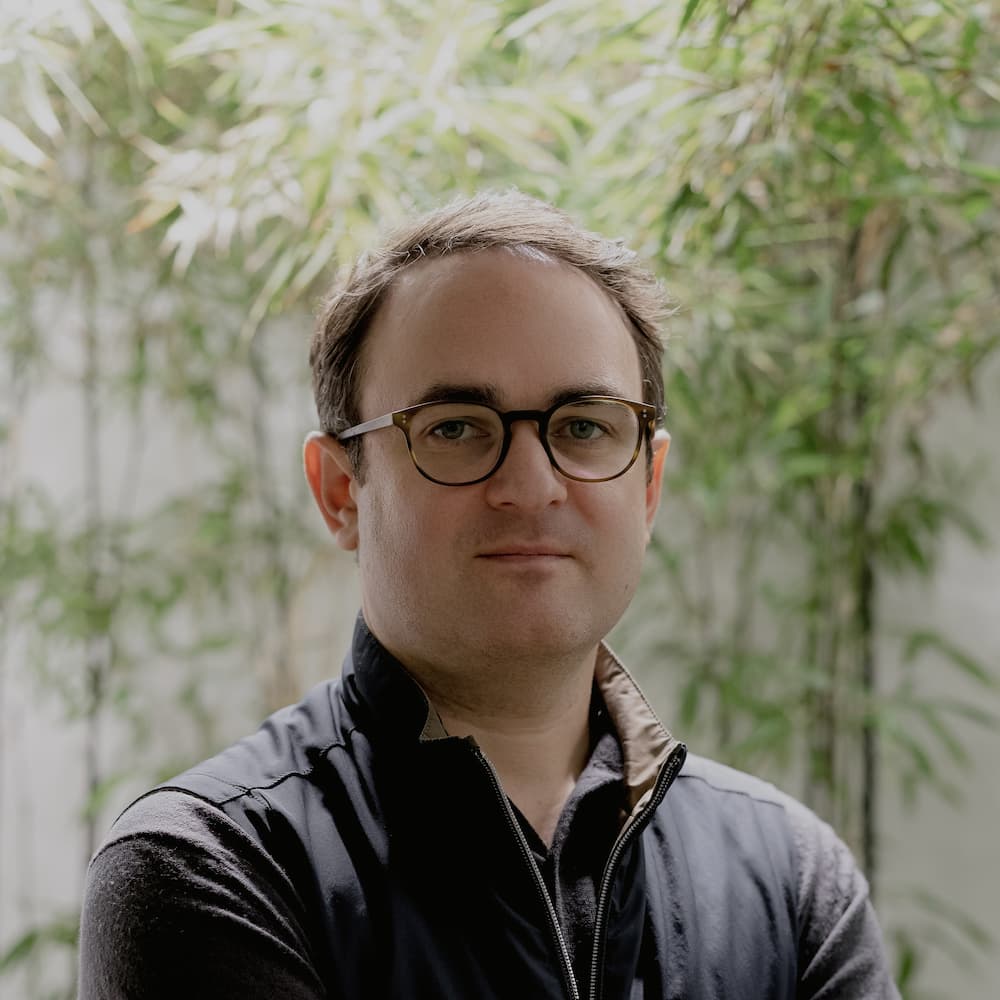
The following article comes from Alex Branton (main picture),
chief investment officer, Nodem
Capital. He writes about the ways in which families with
private fund investments can use them as collateral for loans,
and examines why families consider these options, how they arise,
and the risks and costs.
The editors are pleased to share this content; the usual
editorial disclaimers apply to views of guest writers. To comment
and enter the conversation, email tom.burroughes@wealthbriefing.com
and amanda.cheesley@clearviewpublishing.com
A family can hold a great deal of value in private funds and
still be short of cash in a particular quarter.If the funds
have not [been] distributed, something may need to be paid,
or something worth buying has appeared. Selling fund interests in
the secondary market is one answer. Borrowing against them is
another.
That second option is less widely understood, so it is worth
setting out plainly. NAV stands for net asset value. In the
lending discussed here, a lender looks at a family's portfolio of
private fund interests, decides how much of that value it is
prepared to advance against, and lends to a vehicle the family
controls. The family keeps the investments. In exchange it grants
the lender security rights over them and over the cash they
produce, and it repays principal, interest and fees. This is
borrowing by the investor. The underlying funds are not borrowing
anything.
The part families tend to discover late is that this cannot be
switched on when it is needed. I want to explain why, because the
preparation is the whole difference between an option you have
and an option you merely like the sound of.
Why families look at it
The obvious use is defensive. A payment falls due before the
portfolio produces cash, and borrowing avoids selling good assets
into a secondary market that may be pricing them at a
discount.
The less obvious use is opportunistic and, in my experience,
it is at least as common. A co-investment appears with a short
fuse. A manager the family has wanted access to for years reopens
briefly. Several funds call capital in the same month, and the
family would rather not hold a large cash drag all year in case
they do. Liquidity that can be drawn in days rather than raised
over months changes what a family can say yes to.
What the family gives up
Worth being clear about this early, because it is not a free
option.
The lender will want the cash the funds pay out to arrive
somewhere where it has rights over. In many structures,
distributions go to the lender before they reach the family, and
that can apply from day one on a perfectly healthy loan rather
than only when something has gone wrong. The term for it is a
cash sweep. Establish whether there are carve outs so that
capital calls, taxes and running costs can still be met.
The amount that can be borrowed also moves. Lenders do not
advance against the headline figure on your quarterly statements.
They advance against a defined and smaller number, after
concentrated positions are excluded or capped, currencies
adjusted and existing debt counted. If valuations fall, that
number falls, and the family needs to know in advance what that
does to the loan and what is required to put it right.
And there is a cost for holding an arranged facility you
have not used, usually a fee on the undrawn amount.
Why it takes time to arrange
The credit view is normally the quickest part. On a diversified
portfolio we can form one fairly rapidly. What takes the time is
legal and structural, and three things.
First, the fund documents. Limited partnership agreements often
restrict transfers and pledges. Many are drafted widely enough so
that pledging the vehicle which holds the interests counts as a
restricted transfer too. Somebody must read them. Across
20 funds that is a genuine exercise.
Second, who is actually borrowing? "The family" is not a
borrower. The entity that owns the fund interests, the vehicle
that would borrow, any guarantor and the people who benefit from
the money are frequently different parties, and trusts complicate
it further. Counsel must confirm who may borrow, who may pledge,
and whose approval is needed.
Third, the plumbing for the cash. The lender needs rights over
the account the fund distributions land in, which means
agreements with your custodian bank and sometimes
acknowledgements from the fund managers themselves. Documentation
involving banks you do not control is the most common reason why
a timetable slips.
None of that is hard in principle. It is slow, and it does not
respond well to pressure.
What can be reused?
Here is the encouraging part. Much of that groundwork holds good
afterwards, provided it is kept current.
The entity analysis stands until the structure changes. The
review of your existing fund documents does not need repeating
for those funds. Account arrangements, once in place, stay in
place. A family that has done this work is in a materially better
position next time, whether that means increasing a facility,
replacing it or simply drawing on one that already exists.
It does not make future borrowing automatic. New fund commitments
need reviewing. Consents can need refreshing. Lenders will still
underwrite, approve and set conditions. Preparation removes
friction rather than replacing credit assessment.
It also helps to separate three decisions that are often run
together. Understanding whether the portfolio could support
borrowing is one thing, and relatively inexpensive. Negotiating
and signing a committed facility is a second, with real cost and
real obligations. Drawing the money is a third. A family can stop
after the first and still be far better placed than one that has
done nothing.
Four questions for your advisors
If this is worth exploring, these are the questions to put to
your finance and legal teams before talking to any lender.
Which entity would borrow, and does it have the power to borrow
and to pledge? Which fund interests could be pledged, and which
carry restrictions needing consent? What would a lender treat as
eligible value, as against the reported figure? And what would
repay the facility, with what fallback if the expected
distributions arrive late?
Clear answers to those four do not guarantee a facility. They do
mean that the conversation starts from a position of knowledge
rather than discovery, which is usually the difference between an
option a family can rely on and one it cannot.
The families who handle a liquidity need are rarely the ones
who moved fastest once it arrived. They are the ones who did the
unglamorous work in a quiet quarter, when nobody was under
pressure and the fees could be negotiated properly.
About Nodem Capital
Nodem Capital provides NAV
financing and GP financing from $10 million to $100 million and
above, working with family offices and private markets investors.
Its mandate excludes single asset lending, and loan to value on a
diversified portfolio is usually in the region of 10 per cent to
40 per cent of eligible value. Nodem Limited is an asset
manager authorized and regulated by the Financial Conduct
Authority, FRN 1017481, company number 15661530, registered in
England and Wales.
Disclaimer
This article is general information about financing structures.
It is not investment, legal or tax advice, not a recommendation,
and not an offer of financing. Readers should take their own
professional advice. Any terms described are indicative and every
transaction depends on the relevant fund and facility documents.