


Technology
ANALYSIS: Removing A1 Gender Biases In Wealth Sector
Women typically outlive men and their financial needs can differ, but without due care, wealth managers' AI tools will operate on established biases in the data. We talk to a US-based figure in the tech and wealth sector who is trying to find a path forward.
(An earlier version of this article appeared on Friday in our North American news service. The relevance of the topic is global, and as examples below show, evidence from around the world feed into the story.)
AI has been part of industry conversations for long enough for
the expression “garbage in, garbage out” to be a well-known
point. This technology is only as objective as the information
that it feeds on.
It might be supposed that artificial intelligence offers Olympian
standards of objectivity and balance, but the reality is that
biases can be absorbed and cascade through the system. As an
example of the concerns, a paper by academics at Singapore
Management University, published in May last year, said that
AI can also be freighted with gender bias: “Despite
AI's potential to enhance sectors like healthcare, education, and
business, it often mirrors reality and its societal prejudices,
and can manifest itself through unequal treatment in hiring
decisions, academic recommendations, or healthcare diagnostics,
systematically disadvantaging women.”
What all this means is that while AI is a marvel and use cases
multiply in sectors such as private banking and wealth
management, users must think carefully about how they employ AI.
Critical reasoning, alertness and curiosity among flesh-and-blood
humans remain vital.
These issues are front of mind for Shubhi Rao (pictured below),
founder and CEO of Uplevyl, an AI company in the
US that builds vertical knowledge layers through a gender lens,
relevant for workplace rights, financial decisions and
reproductive health. Uplevyl was founded in 2021. Rao, based in
Austin, Texas, argues that there is a hidden gender gap in AI
adoption that influences financial advice, wealth building,
and access to quality planning.
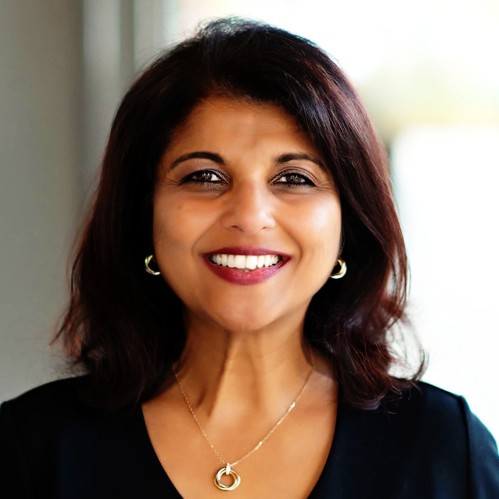
Shubhi Rao
Women's financial plans often fall short, and the wealth
management sector must adapt, she told this publication in a
call. One factor is that many financial plans tend not to capture
that women typically outlive men, requiring investment to
accommodate this.
“AI is as good as the datasets that power it. If you think of
frontier models…the datasets powering these models are scraping
from the internet. None of them are seeing what we should use for
specialised applications,” she said. “You tend [with women] to be
heavier on the advisor's side of the table on their services than
on the investment side.”
Rao brings experience from a number of fields, including
economics. She is also an honorary advisory council member
of the Federal Reserve Bank of San Francisco, and has served as
an Economic Council board member of that institution. She is also
a contributor to Forbes magazine.
Assumptions in the data
A Cerulli survey of affluent investors released in in
September 2024, for example, found that 50 per cent of affluent
women investors rely heavily on an advisor, against 34 per cent
of men. Women face higher lifetime healthcare costs in
retirement, largely because they live longer, she said, and this
will reflect in how they think of finances. HealthView Services'
2026 report puts women's retirement healthcare costs at about 15
per cent higher than men's on average.
“At the moment, AI models don't reflect this,” Rao
said.
Biases by humans can be multiplied by AI.
In 2019, an article by Kings College London referred to research
from Dr Ylva Baeckstrom of King’s Business School. It found that
“male and female financial advisors make judgements about wealthy
clients based on their own and their client’s gender and give
different recommendations as a result.” Dr Baeckstrom, a
former private banker, based her research on her work with 129
UK-based investment advisors specialising in HNW clients.
Switching back in the US, a report this year from Stanford and
MIT found that AI chatbots give women 3 percentage points less
equity exposure, costing them roughly $60,000 in simulated
retirement wealth by age 60. The team behind AI Financial
Advice: Supply, Demand, and Life Cycle Implications,
released as MIT Sloan Working Paper 7377-26 in May 2026,
simulated the life of a virtual saver following advice from
GPT-5.2 and Gemini 3 Flash.
Such results show that using AI models in wealth management
must be done carefully, Rao said.
“The MIT and Stanford study found that after a job loss the
models recommend cutting spending by about as much as income
falls, and that more than 98 per cent of recommended retirement
withdrawals sit at or below a 4 per cent rule,” she said. “None
of these studies test widowhood or other life-event sequences. A
widow's first year is a series of dated, partly irreversible
decisions that depend on where she lives, and that is where we
focus.”
“These are systemic issues,” Rao said. “There is limited data on
gender differences in finance to power algorithms at the moment,
and we have not found a published benchmark for life-event
guidance.”
Her comments come as the wealth industry, still a relatively
male-dominated one, needs to adjust as more women inherit and
create wealth. This news service has covered such issues from a
variety of perspectives, as seen
here and
here.
What is to be done?
Rao argues that AI vacuums data from the open internet, which is
a sort of horizontal model. Instead, there is a need for the
technology to be placed in more vertical “closed” structures or
“multi-tenant” ones.
“Closed means the guidance is drawn from a curated,
source-verified body of rules that we maintain, with no reliance
on what a model absorbed from the open internet,” Rao said.
“Multi-tenant means each firm that uses the platform is its own
tenant, with its own configuration and boundaries. The system is
stateless, so it holds no client data between calls.”
Life events
As part of this approach, Uplevyl is mapping the rules behind the
decisions that each life event triggers for women, starting with
widowhood across US jurisdictions, for example.
“Each life event sets off a different chain of decisions,
deadlines and rules, and which rules apply depends on where a
person lives and what accounts she holds. We are mapping the
rules that decide what a person must do, and by when, after a
life event, for the jurisdiction they live in,” Rao said. “The
list of life events is open-ended. Widowhood comes first because
it is the hardest. A surviving spouse can face survivor benefit
claims, inherited retirement account elections, a change in tax
filing status, Medicare premium adjustments, life insurance
claims and state probate rules within months, each with its own
deadline, and some choices cannot be reversed.”
“The platform is designed to take the life event and the
jurisdiction and return the decisions in sequence, with deadlines
and flags for when a tax, legal or insurance specialist is
needed. The advisor stays in charge of the relationship. The
architecture extends to divorce, retirement, disability and other
life events.
“We need to create workflows that are specific for
advisors…frontier AI models are not designed for it,” Rao
continued.
“In our conversations with advisors, women tend to use more of
the advisor's time on life events,” she said.
Uplevyl has a team of 25 and four advisors, and its clients are a
combination of enterprise and non-profit organisations. Its
knowledge layers cover US jurisdictions.
Profitability under pressure
Beyond the gender issue, Rao talked about the pressure that
wealth management is under, in terms of profits.
“Globally, profitability per AuM is declining,” she said. There
is an advice shortage, and the younger generation is less
interested in following a financial advisory career path. A lot
of those who enter the field tend to leave, she said. “It looks
as if a perfect storm is coming.”
As evidence, Rao cited the 2025 Global Asset & Wealth
Management Report of PwC which surveyed 300 firms in 19
countries. It found that profit per dollar of assets under
management fell 19 per cent since 2018, with a further 9 per cent
decline expected by 2030. Expenses absorb 68 per cent of each
dollar.
The picture for advice shortages varies by market. In the US,
McKinsey estimates a shortfall of roughly 100,000 advisors by
2034, within a range of 90,000 to 110,000. In the UK, the
Financial Conduct Authority has said that advisor numbers have
held at around 31,000 since 2021; the average advisor is in their
late 40s.
The challenge of profitability was highlighted recently in the UK
by BWC
Benchmarking in its
annual study of performance of the UK sector, pointing to
relatively low net organic growth once M&A activity is taken
out.
The stakes
Rao said the importance of ensuring that AI works for all sides
of society is more important than ever. She noted how in May, for
example, that Schwab's chief executive, Rick Wurster, said he
sees AI becoming a front door for clients, including those below
the $1 million needed for a dedicated advisor. This means that
generative AI is about to sit between firms and a much larger
group of clients.
A Harvard Business School working paper drawing on more than
300,000 respondents estimates generative AI adoption at 47.8 per
cent for men and 39.3 per cent for women.